What Insurance Adjusters Look for on Your… | Wannamaker
After a storm rolls through San Antonio, the insurance adjuster becomes the gatekeeper between you and a new roof. Their inspection typically lasts 30 to 90 minutes, and in that window, they're making decisions that could mean the difference between a full roof replacement and a claim denial. Most homeowners have no idea what adjusters are specifically looking for — or how to prepare. That's a problem, because what gets documented during that visit is essentially your entire case.
The Adjuster's Checklist: What They Inspect First
Insurance adjusters aren't freelancing up there. They follow a structured inspection protocol, and most major carriers in Texas — State Farm, USAA, Allstate, Liberty Mutual — use similar frameworks. Here's the breakdown of what they're evaluating:
1. Hail Impact Marks on Shingles
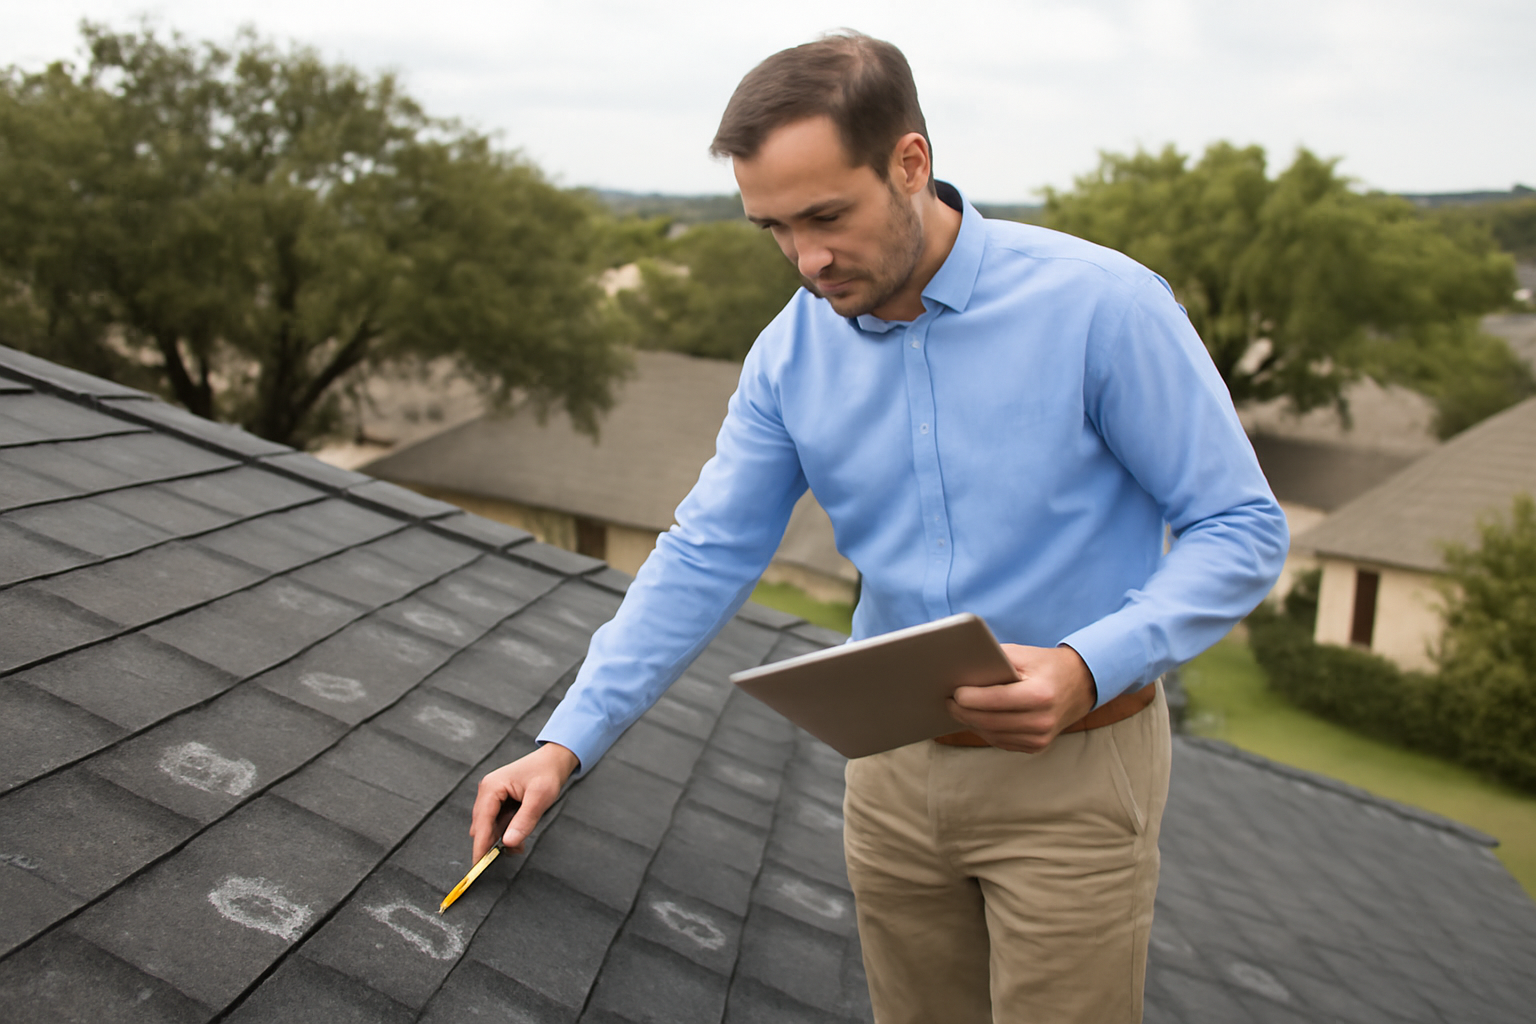
This is the big one in San Antonio. Adjusters look for circular or irregular impact marks where granules have been knocked loose, exposing the dark asphalt mat underneath. On asphalt shingle roofs, they'll run their hand across the surface to feel for soft spots — a telltale sign that the fiberglass mat beneath the granules has been fractured. They'll typically mark confirmed hits with chalk and count the number of impacts per 10-foot-by-10-foot "test square." Most carriers require 8 or more hits per square to justify replacement of that slope.
2. Wind Damage and Lifted Shingles
With the recent Wind Advisory affecting Kerr, Bandera, Kendall, Blanco, and Hays counties on October 15th — and high wind warnings in nearby areas — wind damage is a real concern right now across the Hill Country and greater San Antonio. Adjusters look for shingles that are creased, lifted, or completely missing. They check whether the seal strip (the adhesive line that bonds each shingle to the one below) has broken. A creased shingle may lay flat and look fine from the ground, but once that seal is broken, it's compromised and will eventually fail.
3. Metal Components: Vents, Flashing, and Gutters
Adjusters always inspect the "soft metals" on your roof — pipe boots, ridge vents, exhaust caps, flashing around chimneys, and gutters. These dent far more easily than shingles and serve as corroborating evidence. If your aluminum vents are peppered with dents but the adjuster can't find shingle damage, they'll question whether the storm was severe enough. Conversely, dented metals alongside shingle hits strengthen your case significantly.
4. The Age and Condition of Your Roof
Here's where it gets contentious. Adjusters are trained to distinguish between storm damage and pre-existing wear. They'll note granule loss in gutters and downspouts (normal aging), blistering (a manufacturing or ventilation issue), and curling at shingle edges (heat-related deterioration). If your roof is 15-plus years old, expect the adjuster to scrutinize more carefully. They're looking for reasons to attribute damage to age rather than the storm. This is where having your own documentation matters enormously.
What They Check Beyond the Shingles
A thorough adjuster doesn't stop at the roof surface. They'll also inspect:
- Fence tops and AC units. These ground-level items show hail impact patterns and confirm storm direction and severity.
- Window screens and siding. Dents, tears, and pockmarks on these surfaces corroborate roof-level damage.
- Interior ceilings and walls. Water stains, bubbling paint, or damp drywall indicate active leaks — evidence that the roof's waterproofing layer has been breached.
- Attic and decking. Some adjusters (not all) will check the attic for daylight penetration, water staining on decking, or signs of inadequate ventilation that could contribute to premature failure.
How to Prepare Before the Adjuster Arrives
The single most impactful thing you can do is have a qualified roofer inspect your roof before the adjuster shows up. Not to game the system — but to ensure nothing gets missed. Adjusters are human. They have 3-4 inspections scheduled that day. They might spend 20 minutes on your roof when it needed 45. A contractor who's already identified and documented damage can walk the roof alongside the adjuster and point out areas that might otherwise be overlooked.
At Wannamaker Roofing, we offer a free roof inspection specifically for this purpose. We photograph every area of concern, document it with measurements, and provide a report you can share with your adjuster. This isn't about inflating claims — it's about making sure legitimate storm damage gets properly recorded.
Other Steps to Take
- Photograph everything from the ground. Capture fallen debris, displaced shingles, dented gutters, and any visible damage before temporary repairs are made.
- Don't make permanent repairs before the inspection. Tarping a leak is fine and expected. Replacing shingles before the adjuster sees the damage can torpedo your claim.
- Keep a storm timeline. Note the date, approximate time, and type of storm. Check local weather reports for hail size measurements. This data matters if there's a dispute about what storm caused the damage.
- Know your policy. Understand whether you have Replacement Cost Value (RCV) or Actual Cash Value (ACV) coverage, and whether your deductible is a flat dollar amount or a percentage of your dwelling coverage.
What Happens When You Disagree with the Adjuster
It happens frequently — an adjuster approves a partial repair when the roof clearly needs full replacement, or they deny the claim entirely. You have options. Texas law allows you to request a re-inspection with a different adjuster. You can also invoke the appraisal clause in your policy, which brings in an independent appraiser to settle the disagreement. Having a contractor who understands the insurance claim process on your side makes a significant difference here. We've helped homeowners across San Antonio, Stone Oak, and Boerne navigate supplement requests and re-inspections that resulted in full approvals after initial partial denials.
The Difference Between a Fair Adjuster and a Rushed One
Most adjusters are professionals doing honest work. But after a major storm event — like the wind systems that just swept through the Hill Country — carriers bring in "cat teams" (catastrophe adjusters) from out of state. These adjusters may be unfamiliar with Texas-specific roofing materials, local building codes, or how San Antonio's intense UV exposure accelerates certain types of wear. They're processing high volumes under tight deadlines. That's not a criticism — it's a reality. And it's exactly why having a local roofer present during the inspection protects your interests.
Storm Damage? Get Inspected Before Your Adjuster Arrives
If your property was affected by recent high winds or hail, schedule a free roof inspection with Wannamaker Roofing before your insurance adjuster visit. We'll document every issue, provide a detailed report, and can be present during the adjuster's inspection to ensure nothing gets missed. We've been helping San Antonio homeowners navigate hail damage repair claims since 2012 — and we know what adjusters are looking for because we've walked hundreds of roofs alongside them.
The adjuster's inspection isn't something that happens to you — it's something you should actively participate in. Know what they're checking. Have your own documentation ready. And make sure a qualified contractor has eyes on your roof before the adjuster writes their report. That's not gaming the system. That's being a smart homeowner.